Uganda gambling regulator engages operators on implementation of new 15% withholding tax


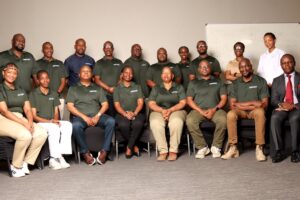
The meeting covered the calculation and administration of withholding tax on winnings, including the treatment of players’ net gains.
Uganda.- Uganda’s National Lotteries and Gaming Regulatory Board (NLGRB) has engaged licensed gaming operators on the implementation of the country’s new 15 per cent withholding tax on betting and gaming winnings.
The engagement, held on Friday, September 11, brought together the NLGRB, Uganda Revenue Authority (URA) and gaming operators to discuss the tax requirements introduced under Section 131 of the Income Tax (Amendment) Act, 2026.
Under the amended provision, persons making payments for betting or gaming winnings must deduct withholding tax at a rate of 15 per cent. The law defines winnings as the difference between the payout and the amount staked, meaning the tax is applied to a player’s net gain rather than the full payout.
The amendment came into force on July 1, 2026, although the legislation was only assented to by President Yoweri Museveni on August 20, after an earlier version was returned to Parliament for reconsideration.
The initial bill exempted winnings from land-based casinos, but Museveni rejected the provision when he returned it to Parliament in July. The revised legislation subsequently removed the land-based casino exemption, while winnings paid by the licensed national lottery operator remain outside the scope of the withholding tax.
Speaking at the engagement, NLGRB chief executive officer Denis Mudene encouraged operators to work with regulators to find practical solutions as the new requirements take effect. He also called for greater adoption of technology across the sector and compliance with regulatory standards, saying digital tools are essential to effective oversight.
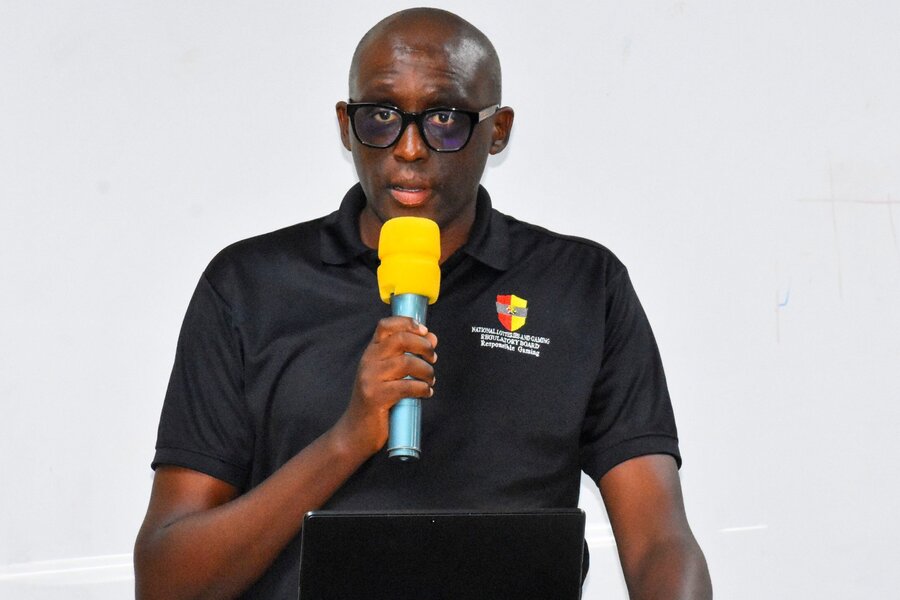
According to Mudene, greater use of technology can support transparency, accountability and fair competition while improving public confidence in the gambling sector.
During the meeting, operators raised questions about the new tax requirements and provided feedback on their implementation.
URA already requires licensed betting and gaming operators to deduct withholding tax from winnings before paying customers and file the relevant returns monthly. The amended Section 131 now extends the requirement from betting winnings to both betting and gaming winnings, with taxable winnings calculated as the difference between the payout and the amount staked.